
Who this guide is for: anyone who has heard that Compound is the "original" DeFi lending protocol and wants to know how it works today before connecting a wallet. It is written for a first-time DeFi user, and it also covers the parts that matter to a more experienced lender, a borrower, a developer or a COMP holder.
We tested this on three real devices (every screenshot was taken live on 16 November 2026, not stock images):
| Device | Width | What we opened |
|---|---|---|
| Desktop | 1440px | Website, Institutional Market page, Compound app (Dashboard, Markets, Rewards, Extensions), docs, governance page |
| Tablet | 1024px | Homepage, Dashboard, Markets |
| Phone | 430px | Homepage, Dashboard, Markets, governance page, docs |
We also connected a throwaway MetaMask wallet that holds no funds to the Compound app and walked through every menu we could reach: Dashboard, Markets, Rewards, Extensions, the network and market selector, and the Institutional Market view. Because the wallet is empty, the Supply USDC and Borrow USDC buttons stay greyed out, so we did not deposit, borrow, sign or approve anything. That means we have no first-hand data on gas costs, transaction speed, liquidation behaviour or the reward claim process. Where a statement comes from the documentation instead of our own click, we write "the docs say".
Quick verdict: Compound III (also called Comet) is a plain, strict lending protocol. You supply one asset such as USDC to earn interest, or you post collateral such as ETH or wBTC and borrow that one asset. It has survived for more than six years, its rules are simple to read, and it keeps all of its parameters under on-chain governance. The trade-offs are real, though: it is now much smaller than Aave and Morpho, many of its 29 markets are tiny, the rates move constantly, and COMP rewards have moved to a third-party site (Merkl). It suits users who want a conservative, easy-to-audit lending venue, not users hunting for the biggest yield.
| Item | Detail |
|---|---|
| Best for | Lenders and borrowers who want a simple, long-running protocol with one borrowable asset per market |
| Fees | No deposit or withdrawal fee shown in the app, the protocol earns from the gap between borrow and supply rates, network gas applies |
| Custody | Non-custodial smart contracts, you connect your own wallet (the new Institutional Market is labelled Early Access) |
| Main chain | Ethereum, with markets also on Base, Arbitrum, Optimism, Linea, Polygon, Ronin, Unichain, Mantle and Scroll |
| Headline rate | USDC on Ethereum: 3.91% supply, 4.53% borrow (16 November 2026, these change every block) |
What Is Compound Finance? (Plain English)
Think of Compound as a pawn shop and a savings account in the same building, run by software instead of people. Some people want to earn interest on coins that are sitting idle. Other people want to borrow cash without selling what they own. Compound connects the two groups automatically. Nobody negotiates a rate: the price of borrowing goes up when many people borrow and down when few do.
In the current version, Compound III, each market has exactly one borrowable asset (called the "base asset"). On the main USDC market, USDC is the base asset. If you supply USDC, you earn interest. If you want to borrow USDC, you must first lock up other assets (ETH, wstETH, wBTC, cbBTC, LINK, UNI and others) as collateral. The docs say collateral does not earn or pay interest, it only sits there to protect lenders.
In plain terms: Compound is a rate-setting machine for loans. Lend USDC and earn the supply rate, or lock collateral and pay the borrow rate. A liquidator closes your loan if your collateral falls too far.
Who built it? The docs describe Compound III as a protocol developed by Compound Labs and the community, and the audit report from 2022 states the same. The protocol is run by token holders through the COMP governance token. The website says Compound has been running for more than six years. The new website, compound.xyz, shows a banner saying the old compound.finance domain will be retired in the coming weeks, and the old address already redirects.
Key facts (16 November 2026):
| Fact | Value | Source |
|---|---|---|
| Total value locked (Compound V3) | $1.073B | DefiLlama (category Lending) |
| Total supply across V3 markets | $1.64B | Compound app, Markets page |
| Borrowed across V3 markets | $578.05M | Compound app, Markets page |
| Collateral posted | $964.21M | Compound app, Markets page |
| Compound V2 TVL (older version) | $81.1M | DefiLlama |
| Homepage "Current TVL" | $1.75B | compound.xyz homepage |
| Homepage "Total Deposits and Loans" | $480B | compound.xyz homepage |
| COMP price | $18.00 | CoinGecko |
| COMP market cap | $179.98M | CoinGecko |
| Chains with V3 markets | 10 | Compound app market selector |
Why the numbers differ: the app says total supply is $1.64B, of which $578M is currently lent out. Subtract the borrowed part and you get roughly $1.06B, which matches DefiLlama's $1.073B TVL. The homepage shows a bigger "Current TVL" of $1.75B and a headline of $480B for "Total Deposits and Loans" without saying how it is counted (it looks like a cumulative figure). We could not reproduce either number from live data, so we use the app and DefiLlama figures in this review.
How Compound Looks on Your Device
Compound is split into several sites. compound.xyz is the marketing site, app.compound.xyz is where you connect a wallet, docs.compound.xyz is the developer documentation, and governance runs on a separate site (Tally, which now calls itself Cactus). We checked all of them on three screen sizes.
On a Laptop or Desktop Computer (1440px wide)
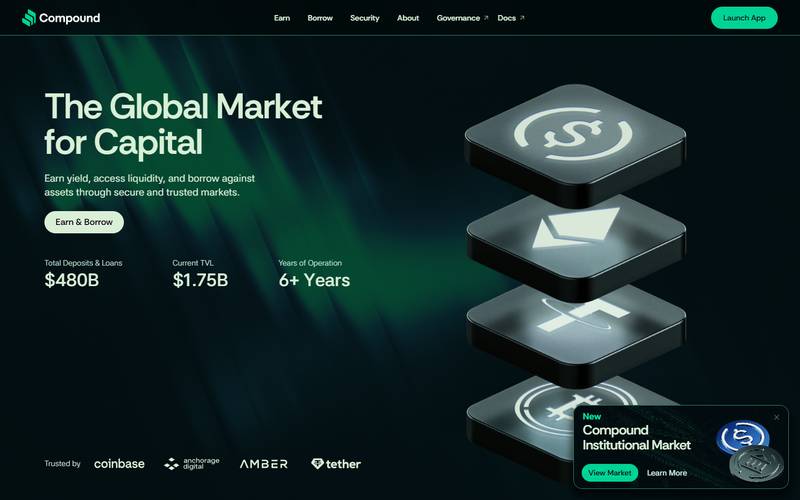
The homepage opens with the headline "The Global Market for Capital" and a short line about earning yield, accessing liquidity and borrowing against assets. The top menu has Earn, Borrow, Security, About, Governance and Docs, plus a Launch App button. Under the headline, a counter row shows Total Deposits and Loans, Current TVL and Years of Operation (6+ years). A "Trusted by" row lists Coinbase, Anchorage Digital, Amber and Tether. These logos are the site's own claim, and we did not verify any of those relationships.
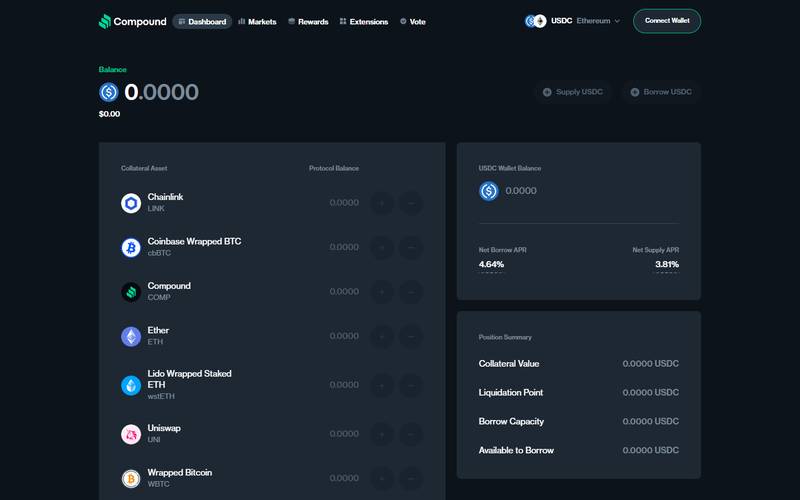
The app uses a dark layout with five tabs: Dashboard, Markets, Rewards, Extensions and Vote.
On a Tablet: iPad (1024px wide)
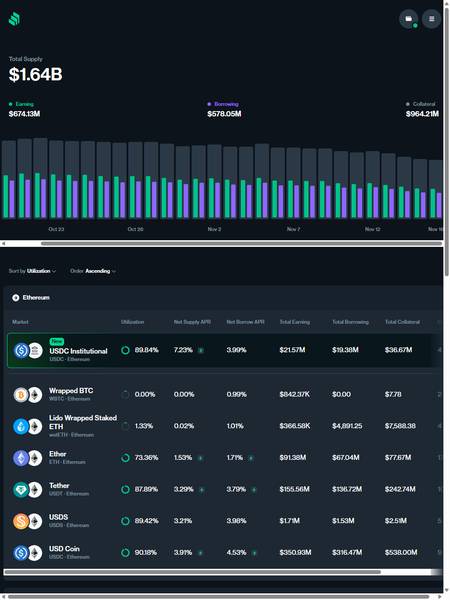
The homepage keeps the full desktop menu and the page is not cut off. The app dashboard becomes a single column: the balance on top, then two wide Supply USDC and Borrow USDC buttons, then the collateral list. A thin horizontal scroll bar appears at the bottom of the page, which means something is a little wider than the screen. The Markets table is wider than a tablet screen, so the last columns (Collateral Assets) are cut off and you must scroll sideways to see them.
On a Phone: iPhone 16 Pro Max (430px wide)
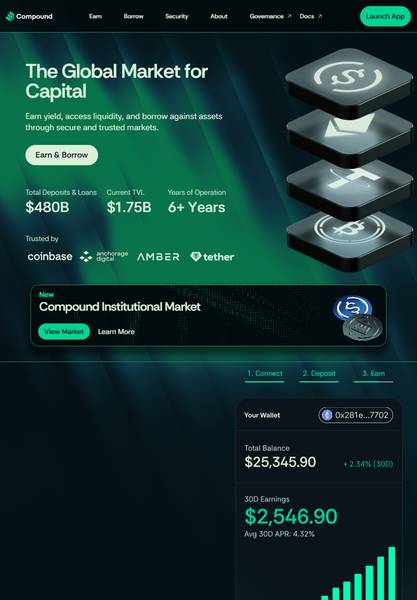
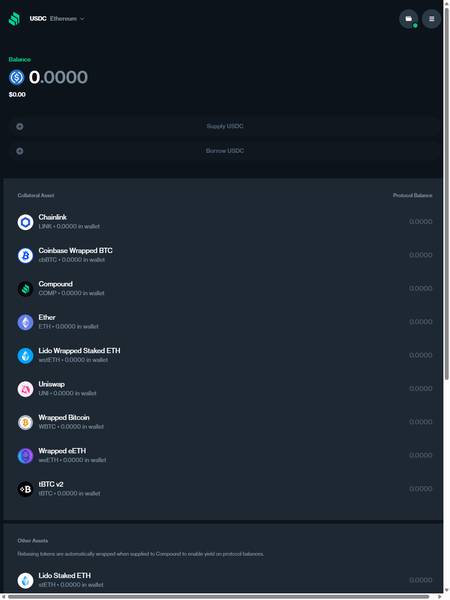
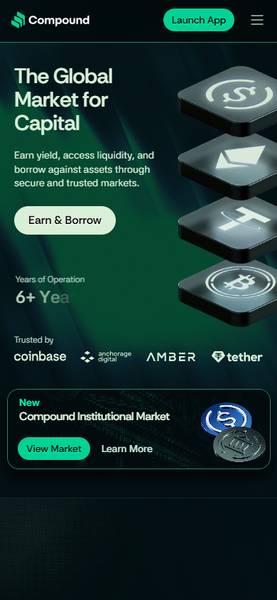
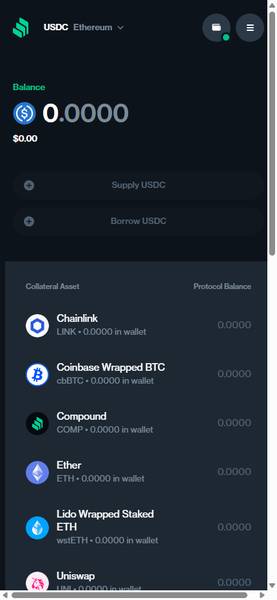
On a phone the website collapses into a hamburger menu with a Launch App button. One flaw we noticed: the statistics row on the homepage (Total Deposits and Loans, Current TVL, Years of Operation) is squeezed so that only "Years of Operation" shows, and its number is clipped ("6+ Yea"). The two money figures are not visible on this screen size. In the app, the header shrinks to the market selector plus a wallet icon (with a green dot when connected) and a menu button. The dashboard stays usable with large buttons, but there is also a horizontal scroll bar, so the layout is not perfectly fitted to the phone.
Connecting Your Wallet to Compound (Step by Step)
We used a MetaMask wallet created only for testing. It holds no money and we never signed anything.
- Open app.compound.xyz. A pop-up titled "You are about to leave Compound" appears first. It says COMP rewards are now claimed on Merkl and offers a Proceed button. We dismissed it with the Escape key and stayed on the dashboard.
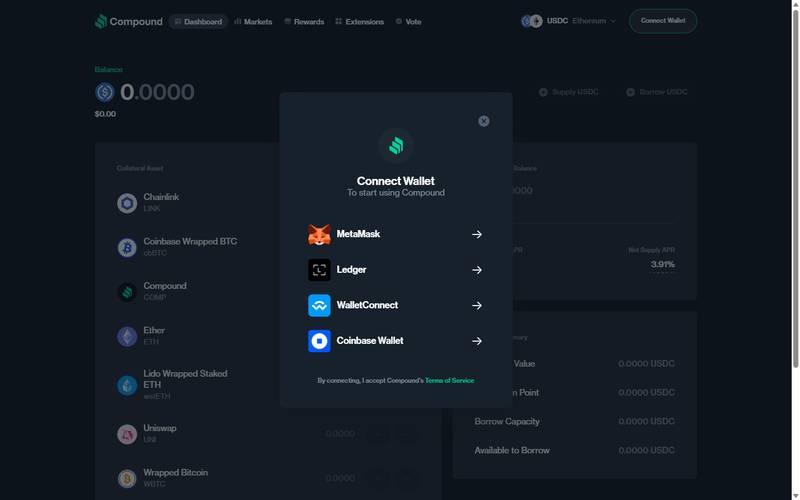
- Click Connect Wallet (top right). A window lists MetaMask, Ledger, WalletConnect and Coinbase Wallet, with a line saying that by connecting you accept Compound's Terms of Service.
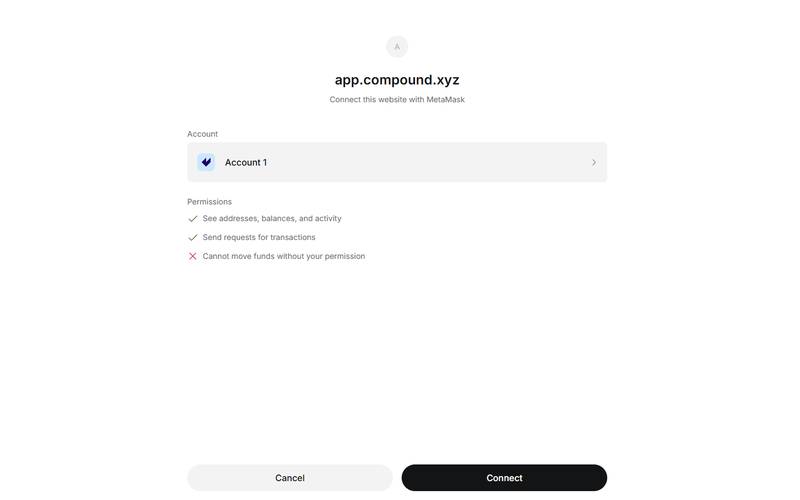
- Choose MetaMask. MetaMask opens its own request: "Connect this website with MetaMask". The permissions screen says the site can see addresses, balances and activity and send requests for transactions, but cannot move funds without your permission.
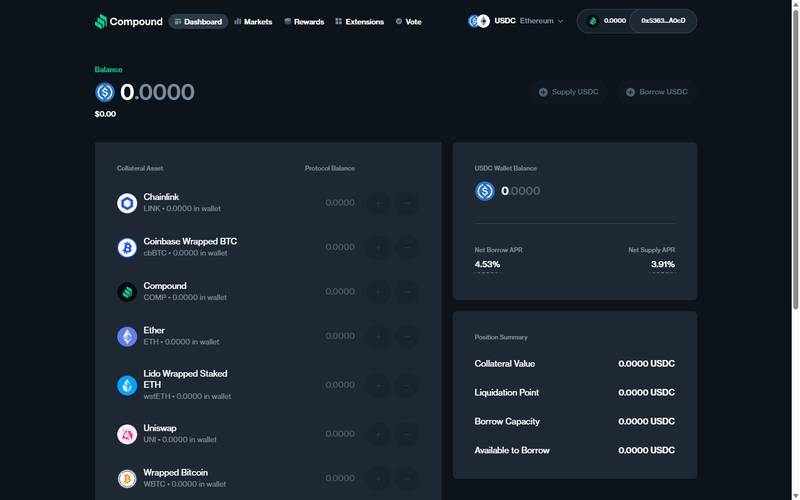
- Click Connect in MetaMask. The app header now shows a small token balance (0.0000) and a shortened address (the test wallet appears as 0x5363…A0cD).
Connecting did not prompt a transaction in our test. The app also contains a "Confirm Network Switch" prompt that appears if your wallet is on an unsupported network.
Safety tip: the real address of any wallet should never be shared. Use a separate wallet for testing, and never approve a transaction you do not understand.
Compound's Core Features at a Glance
| Feature | What it does | Tested by us |
|---|---|---|
| Supply the base asset | Deposit USDC, ETH, USDT and others to earn the supply rate | Viewed only (buttons greyed with an empty wallet) |
| Borrow the base asset | Lock collateral and borrow against it | Viewed only |
| Collateral list | Shows each asset with its collateral and liquidation factor | Yes, read in the app |
| Markets page | Compares 29 markets on 10 chains | Yes |
| Market and chain selector | Switches between markets and chains | Yes |
| Institutional Market | Higher borrowing power for approved suppliers (Early Access) | Page and app view only |
| Rewards | COMP incentives, now claimed through Merkl | Yes, we read the page, did not claim |
| Extensions | Optional add-ons: Advanced Transactions, Comp.Vote, DeFi Saver | Yes, we opened one |
| Vote | Link to governance on Tally | Yes, we read the public page |
| Compound V2 (legacy) | Older version, listed under Legacy | Seen in the selector only |
Feature 1: Supplying and Earning Interest
What it is: you deposit the market's base asset and your balance grows. In the USDC market on Ethereum, you deposit USDC. The docs say interest accrues every second, so the number on your dashboard moves continuously instead of once a day. The rate is not fixed. It is calculated from utilization, which is the share of supplied money that is currently borrowed.
What the docs say about rates: each market has a "kink". Below the kink, rates rise gently as more of the pool is borrowed. Above the kink, the borrow rate rises much faster to push borrowers to repay and pull in new lenders. Supply and borrow rates use separate curves.
What we saw (16 November 2026, Ethereum USDC market): utilization 90.18%, net supply APR 3.91%, net borrow APR 4.53%. When we first opened the app earlier on the same day, the figures read 3.81% and 4.64%, which shows how quickly the numbers move. Do not treat any rate in this article as a promise.
How to supply (steps from the app and docs, not tested by us):
- Connect your wallet and pick the market from the selector at the top (for example USDC on Ethereum).
- Click Supply USDC on the dashboard.
- Enter an amount, approve the token once if the app asks, then confirm the supply transaction in your wallet.
- Your balance on the dashboard grows over time. Withdraw the same way, using the withdraw option.
With an empty test wallet the Supply USDC button was greyed out, so we could not open the amount box. Everything after step 1 is based on the documentation and the app layout.
One thing to know: when utilization is very high, the pool has little free cash. According to the docs, a lender can only withdraw what is not currently lent out. The Ethereum USDC market was at about 90% utilization when we checked.
Feature 2: Borrowing Against Collateral
What it is: you lock assets as collateral and borrow USDC (or the base asset of the market you picked). The dashboard on the Ethereum USDC market lists nine collateral assets. We read the parameters directly from the app:
| Collateral | Oracle price (16 Nov 2026) | Collateral factor | Liquidation factor |
|---|---|---|---|
| ETH | 1,798.56 | 83% | 88% |
| wstETH | 2,246.95 | 82% | 86% |
| cbBTC | 64,480.88 | 80% | 85% |
| WBTC | 64,361.89 | 80% | 85% |
| weETH | 1,993.29 | 75% | 80% |
| LINK | 9.0961 | 73% | 79% |
| UNI | 5.14 | 68% | 74% |
| COMP | 17.95 | 50% | 70% |
| tBTC v2 | 64,212.05 | 0% | 85% |
How to read this table:
- The collateral factor is how much you may borrow against an asset. At 83%, every $100 of ETH lets you borrow up to $83 of USDC.
- The liquidation factor is the line where your loan can be closed. At 88% for ETH, if your debt grows past 88% of your ETH value, you are in danger.
- The gap between the two (5 points for ETH) is your safety buffer. Volatile assets get lower factors. COMP has the lowest ratio among those that can be borrowed against (50% collateral factor).
- tBTC v2 shows a 0% collateral factor while its liquidation factor is 85%. The app does not explain this on the dashboard. A reasonable reading is that the asset is accepted but cannot currently add borrowing power, but we could not confirm that in the docs, so treat it as unexplained.
The dashboard also has an "Other Assets" section. On the tablet screen it states that rebasing tokens (the example shown is Lido's stETH) are automatically wrapped when supplied, so that they can earn yield on protocol balances.
The Position Summary box on the right shows four numbers: Collateral Value, Liquidation Point, Borrow Capacity and Available to Borrow. All were 0.0000 USDC for our empty wallet. Once you have a loan, watching the gap between your debt and the Liquidation Point is the single most important habit.
How to borrow (steps from the app and docs, not tested by us):
- Click the + button next to a collateral asset and deposit it.
- Check Borrow Capacity in the Position Summary.
- Click Borrow USDC, enter an amount well below the capacity, and confirm.
- Repay later with the same screen, and withdraw your collateral once the debt is cleared.
Beginner warning: borrowing the maximum is how people lose collateral. Keep the debt far below Borrow Capacity so that a normal price drop does not trigger liquidation.
Feature 3: The Markets Page
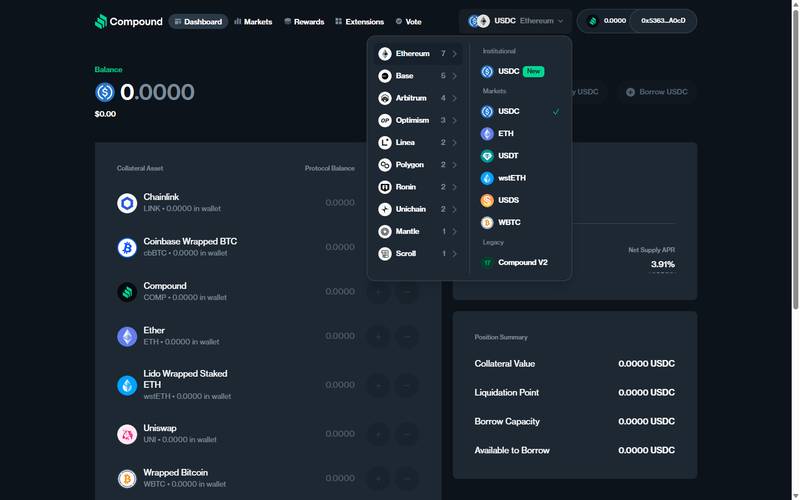
The Markets tab is a public dashboard. The top of the page shows Total Supply $1.64B, alongside Earning $674.13M, Borrowing $578.05M and Collateral $964.21M; these displayed measures should not be added together as a supply split. It also shows a 30-day bar chart (18 October to 16 November). Below it, a table groups markets by chain and shows Utilization, Net Supply APR, Net Borrow APR, Total Earning, Total Borrowing, Total Collateral and the number of collateral assets. You can sort by utilization and reverse the order.
Largest Ethereum markets we read:
| Market | Utilization | Net supply APR | Net borrow APR | Total earning |
|---|---|---|---|---|
| USDC | 90.18% | 3.91% | 4.53% | $350.93M |
| USDT | 87.89% | 3.29% | 3.79% | $155.56M |
| ETH | 73.30% | 1.53% | 1.71% | $91.46M |
| USDC Institutional | 89.84% | 7.23% | 3.99% | $21.57M |
What stands out:
- The three largest markets hold most of the money. The WBTC market on Ethereum shows $842.37K earning and $0.00 borrowed, and the wstETH market shows $366.58K. Many of the 29 markets are barely used.
- The USDC market on Optimism shows 94.17% utilization and 17.38% supply APR (19.80% borrow), but only $1.45M is supplied. A rate that high on a tiny market is a sign of thin liquidity, not an opportunity.
- A small lightning icon appears next to some rates. We did not open its tooltip, so we cannot say exactly what it means. It likely marks incentives included in the "net" figure.

Feature 4: Many Chains, Many Markets
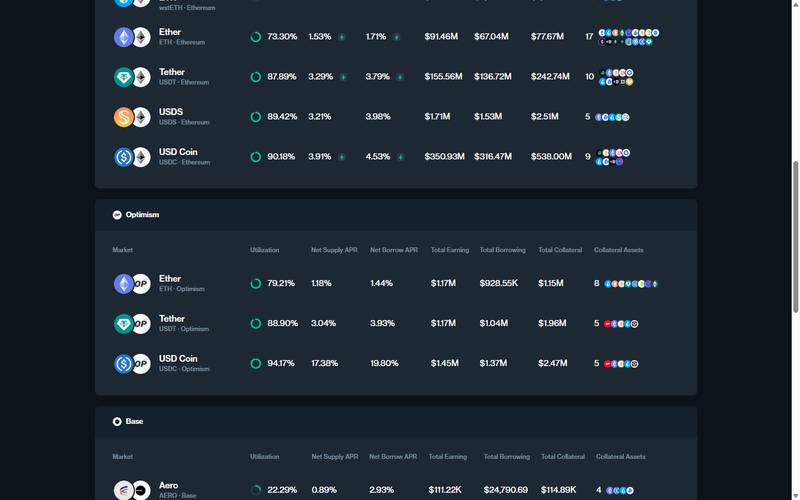
Clicking the market name in the app header opens a two-panel menu. The left side lists chains with the number of markets: Ethereum 7, Base 5, Arbitrum 4, Optimism 3, Linea 2, Polygon 2, Ronin 2, Unichain 2, Mantle 1 and Scroll 1, which adds up to 29. The right side shows the markets for the chain you hover. On Ethereum these are an Institutional section (USDC, tagged New), the regular markets (USDC, ETH, USDT, wstETH, USDS, WBTC) and a Legacy section with Compound V2.
DefiLlama lists the same ten chains for Compound V3, so the app and the third-party tracker agree. The docs add that governance on each non-Ethereum chain works through a bridge: a proposal passes on Ethereum, is relayed to a "Bridge Receiver" on the other chain and waits in a local timelock before it takes effect. That adds a delay, but it also means those chains depend on the bridge working correctly.
Feature 5: The Institutional Market (Early Access)
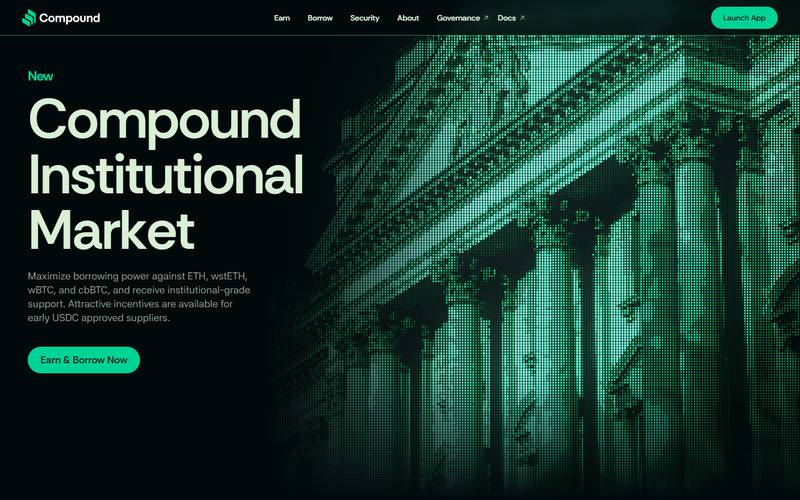
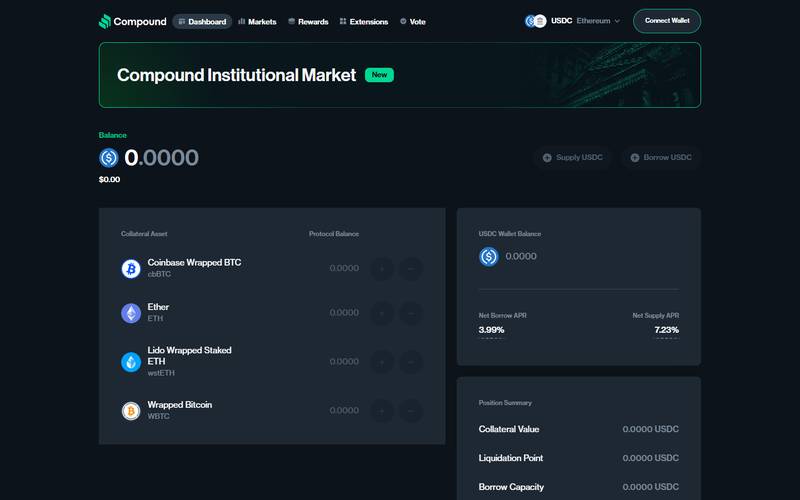
Compound has added a separate Institutional USDC market on Ethereum. The dedicated page says it lets approved suppliers earn incentives and lets borrowers get more borrowing power against ETH, wstETH, wBTC and cbBTC, with "institutional-grade support". The homepage banner and a separate page both label it Early Access.
What the documentation lists for this market:
| Collateral | Borrow collateral factor | Liquidation factor | Liquidation penalty |
|---|---|---|---|
| cbBTC | 81% | 86% | 10% |
| WBTC | 81% | 86% | 10% |
| WETH | 87% | 93% | 5% |
| wstETH | 85% | 92% | 7% |
The Compound site adds that the market has a borrow cap of $10M per collateral. In the app, the Institutional market shows a net supply APR of 7.23% and net borrow APR of 3.99% against 89.84% utilization, with about $21.57M supplied. The supply rate being higher than the borrow rate is only possible because incentives are added on top (the market page says early USDC suppliers get "attractive incentives"). We could not tell how long these incentives last, so the 7.23% should not be treated as a stable yield.
When we opened the institutional view in the app, it showed a banner "Compound Institutional Market" with the same four collateral assets (cbBTC, ETH, wstETH, WBTC). We did not test whether our wallet would be accepted as a supplier, and the docs do not say how "approved" suppliers are chosen, so check that on the site before you plan around it.
Feature 6: Rewards (Now Through Merkl)
The Rewards tab used to be where you claimed COMP incentives. It now shows a banner "Earn and Claim your COMP Rewards via Merkl" and says that how you earn has not changed: Compound calculates the rewards and Merkl is only the place to claim them. Three cards explain the idea (see and claim your rewards, competitive APYs, onchain and verifiable). A "View your Rewards" button sends you to Merkl, and we did not go through to it.
The FAQ explains that Merkl is an independent third-party platform, not operated by the Compound Foundation or Compound DAO. That matters for safety: you connect your wallet to a different website to claim rewards, so check the address carefully.
Do rewards expire? The FAQ says yes. It lists claim windows of 60 days for V2, 180 days for V3 and 30 days for "Seasons" campaigns. We noticed an inconsistency in the V2 answer: the text says the deadline is 60 days after the snapshot, and then says the window closes once "that 30-day period" has elapsed. That is probably a copy error, but it is exactly the kind of detail you want right before an expiry deadline. Check the Merkl campaign page for the real date.
The docs describe an older reward system where rewards accrue inside the market and are claimed through a CometRewards contract. The docs also mention a minimum threshold (baseMinForRewards) before the base asset earns rewards. We did not verify how the new Merkl process maps onto these contracts.

Feature 7: Extensions
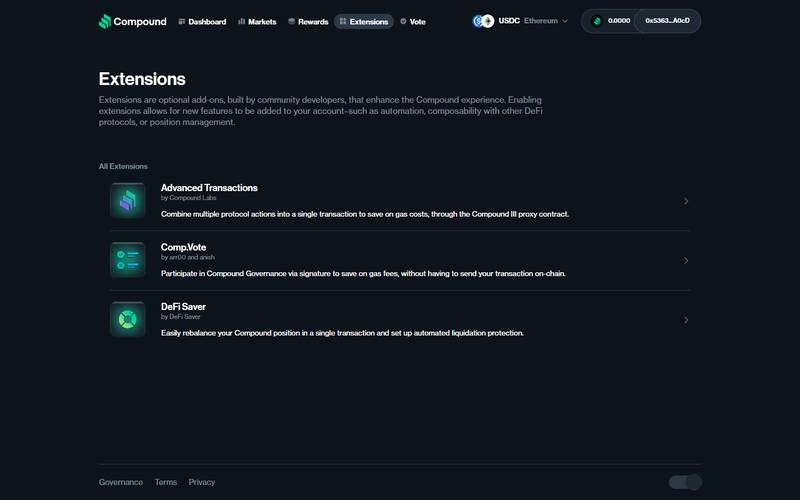
The Extensions tab lists optional add-ons built by Compound Labs or community developers. The page text says they add features such as automation, composability with other DeFi protocols or position management. There are three:
| Extension | Built by | What it does (per the app) |
|---|---|---|
| Advanced Transactions | Compound Labs | Combines several actions into one transaction to save gas, through the Compound III proxy contract |
| Comp.Vote | arr00 and anish | Lets you vote on governance by signing a message, so you do not pay gas for each vote |
| DeFi Saver | DeFi Saver | Rebalances a position in one transaction and can set up automated liquidation protection |
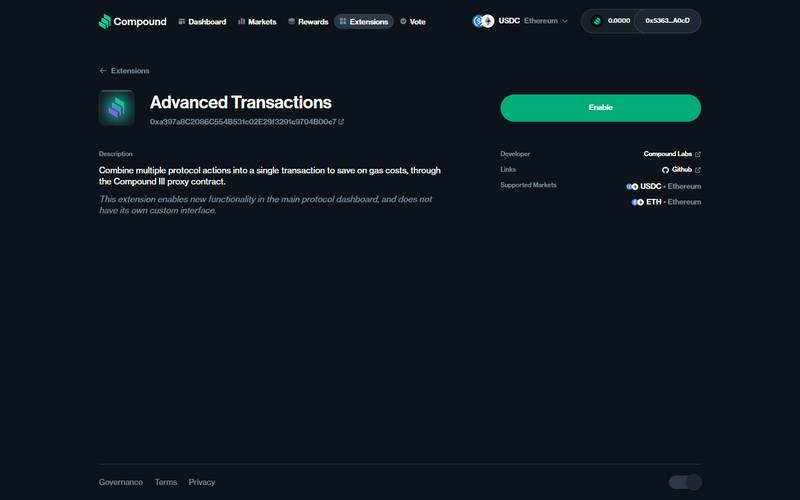
We opened Advanced Transactions. Its detail page shows a contract address, an Enable button, the developer (Compound Labs), a GitHub link and the supported markets (USDC on Ethereum and ETH on Ethereum). A note says the extension adds new functionality to the main dashboard and has no interface of its own. We did not press Enable, because enabling an extension needs a signed transaction.
The docs call this component the Bulker and say it lets you batch actions. Anyone can read its code on GitHub, but note that DeFi Saver and Comp.Vote are third-party tools. Read what permission you are giving before enabling any extension.
Feature 8: Liquidations (What the Docs Say)
We cannot test a liquidation without a real loan, so this section comes only from the documentation. If the value of your borrowed amount rises above what your collateral allows (using the liquidation factor), your account becomes "underwater". Anyone, whether a bot, a contract or a person, can call a function named absorb. The docs say this does three things:
- The protocol takes over the account's collateral and clears the debt using its own USDC reserves.
- The user receives the value of the collateral minus a penalty, paid in the base asset. The docs say the user ends up with no remaining debt and usually a small leftover balance.
- The protocol now owns the collateral. If its reserves fall below a governance-set target, anyone can buy that collateral at a discount, which tops the reserves back up.
What this means for you: liquidation in Compound III is handled by the protocol itself rather than by a race between liquidators who each repay a slice of your loan. The cost to you is the liquidation penalty, which differs by asset and is set by governance. Avoid it by keeping a buffer and by adding collateral or repaying when prices drop.
Feature 9: Documentation and Developer Tools
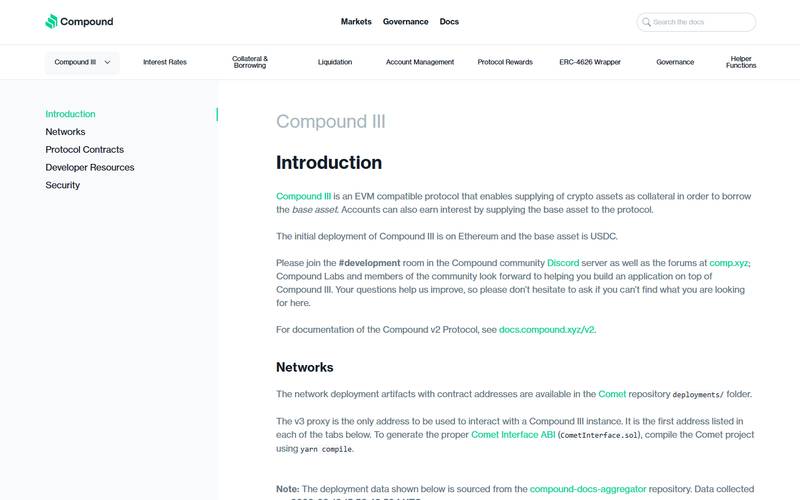
The docs site (docs.compound.xyz) has sections for Interest Rates, Collateral and Borrowing, Liquidation, Account Management, Protocol Rewards, an ERC-4626 Wrapper, Governance and Helper Functions. The introduction page lists every deployment by chain and market, with contract addresses for the proxy, configurator, rewards contract, bulker and governor, and says the deployment data was collected on 16 September 2026 from a "compound-docs-aggregator" repository. That is two months before our visit, so check live data before relying on a parameter.
A few details beginners will not need but developers will:
- The docs say the v3 proxy is the only address you should use to talk to a Comet instance.
- Account management lets you approve a manager to act for you, either with an on-chain call (allow) or with a signed message (allowBySig, using EIP-712).
- The ERC-4626 wrapper lets other apps treat a Compound position like a standard vault token. We did not read the contract and cannot assess it.
The documentation is easy to read on a laptop. On a phone the introduction page works but the code blocks and address tables are narrow.
The COMP Token
What it is: COMP is the governance token. Holders can vote on proposals, or delegate their voting power to someone else. It is not needed to lend or borrow.
Market data (CoinGecko, 16 November 2026):
| Metric | Value |
|---|---|
| Price | $18.00 |
| Market cap | $179,984,133 |
| Fully diluted valuation | $179,984,133 |
| 24h trading volume | $10,082,890 |
| Circulating, total and max supply | 10,000,000 each |
| Price change 24h / 7d / 30d | -0.62% / -10.44% / -17.80% |
| Price change over 1 year | -45.3% |
| All-time high | $854.45 (11 May 2021) |
| All-time low | $14.86 (25 June 2026) |
| Rank by market cap | 166 |
What the numbers say:
- CoinGecko lists the whole supply as circulating, so market cap and fully diluted value are equal. We could not confirm how the 10 million figure splits between holders, treasury and the team, so check the docs and the forum before you assume anything about unlocks.
- The token is far below its 2021 peak ($854.45), down about 98% from there on these figures, and it set a new all-time low as recently as June 2026.
- The app's own oracle price for COMP is 17.95, so the app and CoinGecko agree within a cent or two. The CoinGecko price changes by the minute.
- Liquidity is modest: about $10M of daily volume against a $180M market cap.
What COMP is used for: governance votes, and as a (low-ratio) collateral asset in the Ethereum USDC market, with a 50% collateral factor. COMP incentives for suppliers and borrowers are claimed through Merkl, as described above.
Governance: Who Controls the Protocol
The docs say control sits with the Governor and Timelock contracts, which manage the proxies, the Configurator and the Comet factory. To change a market parameter, a proposal must pass a vote, wait in the Timelock, and then call the Configurator and the proxy admin to deploy an upgraded Comet implementation.
We opened the public governance page (Tally, rebranded as Cactus, with a banner saying so). It showed:
| Governance metric | Value |
|---|---|
| Delegates | 21.18K |
| Token holders | 220K |
| Proposals | 583 |
| Treasury | $48.26M across 59 sources |
| Largest delegate shown | 1.92M COMP (an unnamed address) |
| Second delegate shown | Compound Foundation, 466.82K COMP |
The proposal list included an active proposal to withdraw reserves from a market on Linea (dated 14 November 2026), a proposal pending execution to withdraw reserves from another market (9 November) and an executed risk-parameter update for tBTC (1 November). So the DAO is clearly working on real parameter changes this month. One label on that page says "583 Active proposals now". Only one proposal looked active, so we read the number as the all-time total.
What to watch: voting power is concentrated. The first delegate listed holds about four times as much as the Compound Foundation. We did not connect a wallet to the governance site or vote, and we did not review the voting rules (thresholds, voting period) because the docs page we fetched only gave the technical outline.


Fees and Costs
| Cost | What we found |
|---|---|
| Deposit or withdrawal fee | None shown in the app |
| Borrow cost | The borrow rate (4.53% on Ethereum USDC), paid as interest, not as a one-off fee |
| Protocol cut | The 2022 audit report says the protocol keeps part of the interest as reserves, which is why the borrow rate is higher than the supply rate |
| Liquidation penalty | Set per asset by governance (the Institutional market docs list 5% to 10%) |
| Network gas | Every supply, borrow, repay and withdraw is a transaction. Gas depends on the chain |
| Extensions | Advanced Transactions is meant to reduce gas by batching actions |
| Rewards | Claiming COMP on Merkl is a separate transaction on a separate site |
The spread is the quiet cost. On Ethereum USDC, the borrower pays 4.53% and the lender earns 3.91%, a gap of 0.62 points. Part of that gap funds the reserves that cover liquidations and bad debt. We did not run any transaction, so we have no measured gas figures.
Low-cost tip: on Ethereum mainnet, small deposits can lose a large share of yield to gas. Layer-2 markets (Base, Arbitrum, Optimism) have much cheaper transactions, but the biggest markets are on Ethereum, while the Optimism USDC market had only $1.45M supplied when we looked.
Is Compound Safe? Security and Track Record
Audits. DefiLlama lists two audits for Compound V3 and links to the Compound security page. The docs link to audits by OpenZeppelin and ChainSecurity. We read the OpenZeppelin report, which was delivered to Compound on 14 June 2022 after a review from 13 May to 14 June 2022:
- It found no critical issues and one high-severity issue ("locked assets in contracts"), three medium issues and several low and informational ones.
- The report update says the team addressed all issues by fixing them or by improving documentation and explanations, with some changes still in open pull requests at the time of writing.
- The medium findings included the ability of the governor to approve a party to move assets inside the Comet contract, which shows how much trust is placed in governance.
We did not read the ChainSecurity report, and an audit from 2022 does not cover later additions (new markets, the Institutional Market, the ERC-4626 wrapper). Audits reduce risk. They do not remove it.
Bug bounty. The Compound homepage says the protocol has a bug bounty of up to $1M through Immunefi. We did not check the Immunefi page.
Track record. DefiLlama's hack database lists a September 2021 incident on Compound V2 with a loss of $147 million (classified as an arithmetic or share accounting error). That was the older version. We found no entry for Compound V3 in that database. (DefiLlama’s list also includes a separate entry for Compounder Finance; it is a different project.) Six years of operation without a V3 exploit is a good sign, but it is not a guarantee.
| Risk | What it means for you | How Compound handles it |
|---|---|---|
| Smart contract bugs | A flaw could lock or lose funds | Audits, bug bounty, simple single-asset design |
| Oracle risk | A wrong price could trigger bad liquidations or let someone borrow too much | The app and docs show a price feed per collateral asset, and governance sets caps |
| Governance risk | Token holders can change parameters or approve upgrades | Votes, delegation and a Timelock delay before changes take effect |
| Liquidation risk | You can lose collateral if prices fall quickly | Liquidation factors, penalties and your own buffer |
| Liquidity risk | At 90% utilization, withdrawals depend on borrowers repaying | Rates rise as utilization climbs, which attracts new lenders |
| Cross-chain risk | Non-Ethereum markets depend on a bridge for governance messages | Local timelocks add an extra delay |
| Third-party risk | Rewards are claimed on Merkl, extensions are written by others | Compound says Merkl is independent. Check addresses and permissions |
| Tiny-market risk | Small markets can have extreme rates and thin liquidity | Stick to the largest markets |
Compound vs Competitors
Table note: Every TVL figure below is from DefiLlama, checked on 16 November 2026. TVL is a size measure, not a quality measure; the “How it differs” column is editorial analysis, not a like-for-like score.
| Protocol | TVL | How it differs |
|---|---|---|
| Aave V3 | $13.97B | Pooled lending across many assets and chains, far larger than Compound |
| Morpho Blue | $10.02B | Separate, isolated lending markets that anyone can create |
| SparkLend | $4.09B | Lending linked to the Sky ecosystem, see our Spark review |
| Maple | $2.22B | Institutional credit pools, see our Maple review |
| Compound V3 | $1.07B | One borrowable asset per market, simple rules, governed by COMP holders |
| Fluid | $594M | Lending and borrowing protocol, smaller than Compound V3 |
| Euler V2 | $241M | Lending protocol, smaller than Compound V3 |
| Compound V2 | $81.1M | The older version, now a legacy section in the app |
How to choose:
- Choose Compound if you want a long-running, easy-to-read venue and you are happy with a modest rate on USDC.
- Choose Aave or Morpho if you want the deepest liquidity or more asset choices. They hold roughly 13 and 9 times more value than Compound V3 in this comparison.
- Choose Maple if you specifically want institutional credit yield and accept credit risk (read the Maple review first).
- Choose Spark if you want exposure to the Sky ecosystem (read the Spark review first).
We did not compare live rates across these protocols. Rates change by the minute, so compare them yourself on the day you deposit.
Pros and Cons
| Pros | Cons |
|---|---|
| More than six years of operation | Much smaller than Aave V3 and Morpho Blue |
| Simple design: one borrowable asset per market | Many of the 29 markets are tiny or empty |
| Parameters visible in the app (collateral and liquidation factors) | Rates move constantly and can spike in thin markets |
| Public markets dashboard with supply, borrow and utilization | COMP rewards claimed on a third-party site (Merkl) |
| On-chain governance with Governor and Timelock | Voting power is concentrated among a few delegates |
| Ten chains and an Institutional Market | Institutional Market is Early Access and unclear on who is approved |
| Clear docs and two named audit firms | Core audit we read dates from 2022 |
| Connects with common wallets | Homepage numbers ($1.75B TVL, $480B) do not match DefiLlama or the app |
| Optional extensions that cut gas | The phone layout has clipped statistics and sideways scrolling |
Who Should Use Compound
- Conservative stablecoin lenders who want a transparent, long-running venue and accept a modest rate.
- Borrowers who hold ETH, wstETH, wBTC or cbBTC and want USDC without selling.
- Developers who want a clean lending integration with documented contracts.
- DAO treasuries and institutions who want a governed protocol, and who qualify for the Early Access Institutional Market.
- COMP holders who want to take part in governance.
Who should think twice:
- Anyone looking for the highest yield. Rates on the main markets are single digits.
- Anyone who plans to borrow close to the maximum. Liquidation will cost you part of your collateral.
- Anyone who wants to withdraw large sums from a busy market at short notice.
Verdict
Compound is the plain, careful option among lending protocols. Its main strengths are clarity and survival: the rules fit on one screen, the Markets page shows what is happening, and the protocol has run for more than six years. Its weaknesses are size and focus. Aave and Morpho are many times larger, several Compound markets are almost empty, and the incentives experience now depends on Merkl. The homepage numbers also disagree with independent data, which we would like to see fixed.
For a beginner, the safe way to start is to use the largest Ethereum or Base markets, begin with a small amount, avoid borrowing near the limit and check each approval in your wallet before you confirm it.
Frequently Asked Questions
Is Compound safe?
No DeFi protocol is risk free. Compound III has been audited (we read the 2022 OpenZeppelin report, which found no critical issues), has a bug bounty of up to $1M according to its homepage, and has run for years. Risks that remain include smart contract bugs, oracle errors, governance decisions and liquidation if you borrow.
What is the difference between Compound V2 and V3?
In V2 an asset could be supplied, borrowed and earn interest at the same time. V3 (Comet) gives each market a single borrowable asset, and collateral does not earn interest. The app lists V2 under Legacy, with a TVL of $81.1M on DefiLlama versus $1.07B for V3.
What does the supply APR mean?
It is the yearly rate you would earn if the current rate stayed the same. It does not stay the same. We saw the Ethereum USDC supply APR at 3.81% and then 3.91% within a few hours.
Can I lose my collateral?
Yes. If your debt rises above the liquidation factor of your collateral, your position can be closed and you pay a penalty. Keep your debt well below the borrowing capacity.
Do I need COMP to use Compound?
No. COMP is a governance token. You only need it to vote or delegate, or if you want to use it as collateral.
Where do I claim COMP rewards?
The app sends you to Merkl, an independent platform. Reward campaigns have claim windows (the FAQ lists 180 days for V3), so claim before the deadline.
What is the Institutional Market?
A separate USDC market on Ethereum for approved suppliers, with higher borrowing power on ETH, wstETH, wBTC and cbBTC. The site labels it Early Access.
Is there a mobile app?
We did not find one. The web app works in a phone browser, with some clipped content on the homepage.
Did the 2021 incident affect Compound V3?
The September 2021 incident listed by DefiLlama relates to Compound V2. We found no V3 entry in the hack database.
Did you spend real money?
No. We used a throwaway wallet with no funds. We connected it to the app and visited each page, but we did not sign, approve, deposit or borrow. Gas, speed, liquidation and reward claims are therefore untested.
Quick Links
- Website: compound.xyz
- App: app.compound.xyz
- Institutional Market: compound.xyz/institutional-market
- Docs: docs.compound.xyz
- Governance: tally.xyz/gov/compound
- DefiLlama: defillama.com/protocol/compound-v3
- CoinGecko: coingecko.com/en/coins/compound-governance-token
Disclaimer
This guide is for information only and is not financial advice. DeFi lending carries a risk of total loss, including liquidation and smart contract failure. Figures were captured on 16 November 2026 from Compound's website and app, the Tally governance page, DefiLlama and CoinGecko, and they change often. Items marked "docs say" come from Compound documentation and were not tested by us. We used a throwaway wallet with no funds and did not deposit, borrow, sign or claim anything. Always do your own research.